Proof of Income for Self Employed Car Loan Bad Credit
Self-employed with bad credit? Learn which income documents lenders accept, how to document gig and cash income, and how to build a clean file before applying.
By Benjamin Shaw
You found the car, negotiated the price, and then the finance manager asks for proof of income. For a self-employed borrower with bad credit, that request can feel like a roadblock. Lenders want to see a steady, verifiable stream of money, and self-employment income rarely arrives in a tidy biweekly paycheck. The good news: lenders who work with challenged credit have seen every income pattern imaginable, and there are proven ways to document self-employed earnings that satisfy their requirements. This guide walks you through exactly what documents to gather, how to handle gig work and cash income, and how to prepare a clean income file before you apply through a connection service.
Why Self-Employed Borrowers Face Extra Scrutiny
Car lenders assess risk by looking at two things: your credit history and your ability to repay. Bad credit already flags you as a higher-risk borrower, so lenders lean harder on income verification to offset that risk. When you are self-employed, your income is not automatically reported by an employer, and it can fluctuate month to month. Lenders cannot simply call a payroll department to confirm your salary. That uncertainty is why self-employed applicants often face longer reviews, larger down payment requests, or higher interest rate offers.
The scrutiny is not personal. It is a documentation gap. A W-2 employee hands over two pay stubs and a bank statement, and the lender has everything needed. A self-employed borrower must reconstruct that same picture using tax returns, profit and loss statements, and bank records. The more clearly you can demonstrate stable, repeatable income, the more comfortable a lender becomes. In fact, a well-organized income file can sometimes matter more than the credit score itself when a lender is deciding whether to approve a bad credit auto loan.
There is also a practical reason lenders dig deeper: self-employed borrowers have more flexibility to adjust reported income. A lender wants to see income that is documented consistently across multiple sources. When your tax return, bank statements, and profit and loss statement all tell the same story, your application becomes far more credible. When those documents conflict, underwriters get nervous and may decline the loan or demand additional verification.
Core Documents Lenders Accept as Proof of Income
Most lenders that finance borrowers with bad credit will accept a combination of documents rather than a single pay stub. The exact mix depends on the lender, but the categories are fairly consistent. Understanding what each document proves helps you decide which ones to lead with.
- Federal tax returns: Two years of personal and business returns, including all schedules, are the gold standard. They show reported net income and demonstrate that your business has a track record.
- Profit and loss statements: A year-to-date P&L prepared by you or your accountant shows current income and can supplement older tax returns.
- Bank statements: Three to six months of business and personal statements reveal actual cash flow, including deposits that may not appear on tax returns.
- 1099 forms and invoices: These document payments from clients and are especially useful for freelancers and contractors.
- Proof of business existence: A business license, LLC paperwork, or professional certification confirms you are legitimately self-employed.
Tax returns carry the most weight because they are third-party verified, but they are also the least flexible. If your returns show modest net income after deductions, a lender may struggle to approve a large loan even if your actual cash flow is strong. That is why bank statements and profit and loss statements matter: they can show gross deposits and real-world cash flow that tax returns do not capture. A smart strategy is to provide all three so the lender sees the full picture.
Keep in mind that lenders typically want to see consistency. Two years of tax returns showing similar income levels are far more persuasive than one strong year followed by a weak one. If your income has grown, a profit and loss statement and recent bank statements can bridge the gap and show the trend is positive.
Documenting Gig-Economy and Cash-Based Income
Gig workers and cash-based business owners face a unique challenge: their income is real, but it may not be neatly reported on a traditional tax return. Ride-share drivers, delivery couriers, freelance designers, landscapers, house cleaners, and food truck operators all fall into this category. Lenders know these income streams exist, and many have specific guidelines for evaluating them. The key is to create a paper trail that connects your work to your deposits.
For gig workers, platform earnings statements are essential. Most gig platforms provide annual summaries and monthly payout reports. Download twelve months of payout history and pair it with the bank account where those payouts land. If you drive for a ride-share company, a screenshot of your weekly earnings dashboard combined with matching bank deposits tells a clear story. For cash-based businesses, the burden is higher because cash does not leave an automatic digital trail. In that case, a carefully maintained ledger, receipts, and regular bank deposits become your evidence.
Here is a practical approach to building a gig or cash income file:
- Download twelve months of earnings summaries from every platform or client you work with.
- Match those earnings to deposits in a dedicated business bank account.
- Prepare a simple profit and loss statement that totals gross income and lists major expenses.
- Include your most recent tax return, even if it reports a lower net figure than your actual cash flow.
- Write a brief letter explaining your work history and how your income is generated.
That last item, a short income explanation letter, is often overlooked but can be powerful. It gives the underwriter context that documents alone cannot provide. For example, a driver might explain that they have worked for the same platform for three years and average a certain amount per month. A cash-based contractor might explain seasonal patterns and note that deposits are made weekly. Lenders appreciate clarity, and a well-written letter can smooth over gaps in documentation.
Preparing a Clean Income File Before You Apply
The single best thing you can do for your approval odds is to prepare before you apply. A disorganized application forces the underwriter to work harder, and busy underwriters decline files that create extra work. A clean income file, organized and labeled, signals that you are a serious borrower and makes it easy for the lender to say yes. This matters even more when you apply through a connection service that matches you with multiple lenders, because a strong file can be reused across several applications.
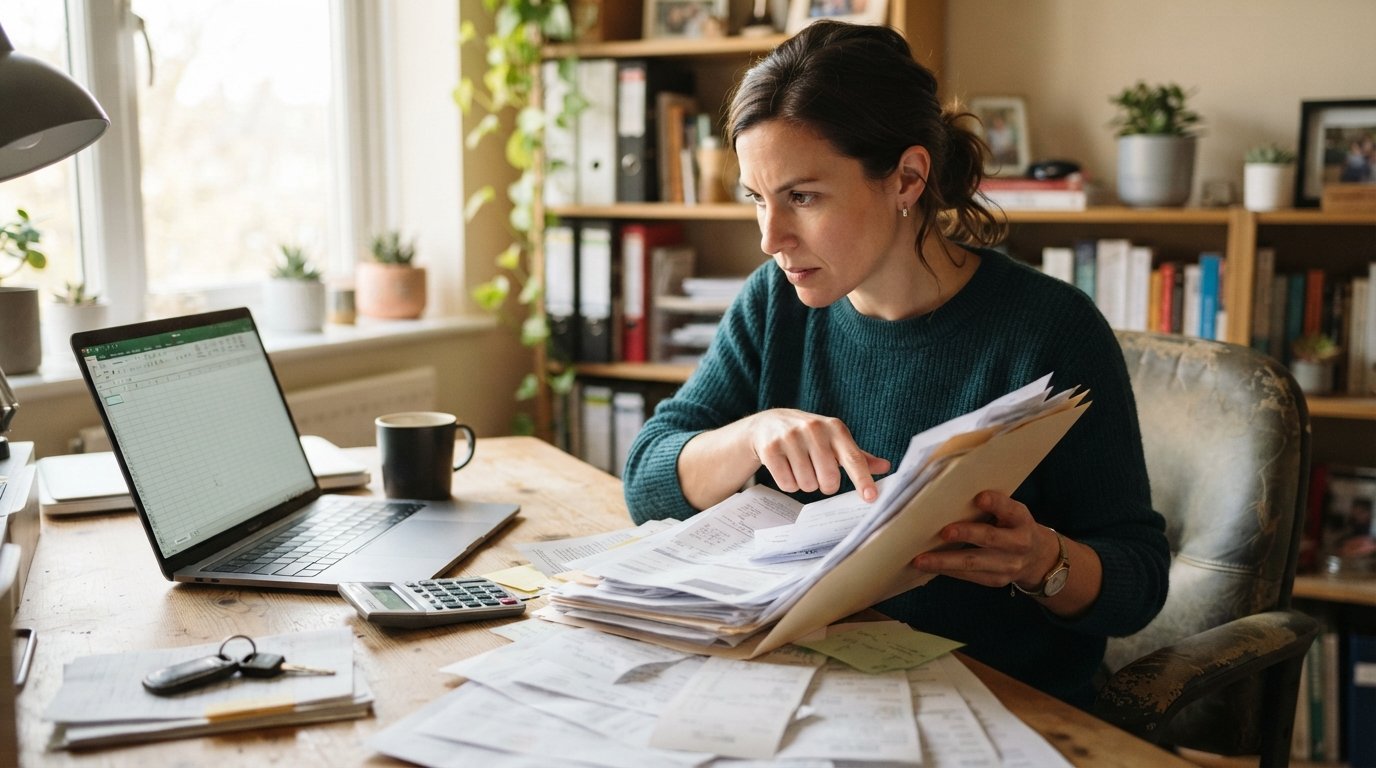
Start by gathering your documents into a single folder, either physical or digital. Label each file clearly, for example, 2024 Tax Return, 2025 Profit and Loss, or Business Bank Statements Jan-Jun. Include a one-page summary sheet that lists your total income, your average monthly deposits, and your years in business. Then review everything for consistency. If your tax return shows one figure and your bank statements show another, be ready to explain the difference, because lenders will ask.
It also helps to know what lenders are looking for before you hand over documents. Most want to see that your income is sufficient to cover the new car payment plus your existing obligations. A common guideline is that your total monthly debt payments, including the car loan, should stay within roughly 40 to 50 percent of your gross monthly income. If your income documentation shows you are near that line, consider a larger down payment or a less expensive vehicle to improve your chances.
Finally, do not wait until you are at the dealership to organize your paperwork. Dealership finance offices are busy, and missing documents can stall a deal for days. Prepare your file in advance, and if you are working with a connection service, have it ready to upload or submit as soon as you complete the request. When you are ready to explore options, StartAutoLoan connects borrowers with lenders who specialize in bad credit situations, and having your proof of income organized will help you move quickly when an offer appears.
Overcoming Common Self-Employment Documentation Hurdles
Even well-prepared borrowers run into snags. One common issue is a decline in income. If your most recent year was weaker than the prior year, lenders may average the two years or focus on the lower figure. You can counter this by providing a current profit and loss statement and recent bank statements that show a rebound. Another common hurdle is heavy business deductions that reduce your reported net income. A lender evaluates net income, not gross revenue, so a tax return showing large deductions can understate your true ability to repay. In that case, an accountant-prepared statement that adds back certain deductions can help, though not all lenders will accept it.
Newly self-employed borrowers face a different challenge. If you have less than two years of self-employment history, some lenders will not count your income at all. Others will accept one year of returns plus a current profit and loss statement and bank statements. If you recently transitioned from a W-2 job to self-employment, include your prior W-2s and pay stubs to show a stable work history. Lenders want to see that your income is not a temporary experiment.
Bankruptcy is another factor that can complicate income verification. If you have a past bankruptcy, lenders will want to see that your income is stable and that you have reestablished credit. Discharge paperwork, current bank statements, and a clean income file all help. Many lenders in the subprime space specialize in financing after bankruptcy, and they are accustomed to reviewing self-employed income. The key is transparency: disclose the bankruptcy upfront and provide documentation that shows you are on solid financial footing now.
How a Connection Service Fits Into Your Strategy
A connection service is not a lender. It is a platform that matches your application with a network of lenders and dealers who are willing to work with bad credit and self-employment income. That distinction matters because it means you are not relying on a single lender's strict guidelines. Different lenders have different appetites for self-employed borrowers, gig income, and cash-based businesses. By submitting one request through a connection service, you can be matched with lenders whose guidelines fit your situation.
When you use a connection service, your income file becomes your calling card. Lenders in the network will review the same documents, so consistency and organization pay off across multiple reviews. Be honest about your income sources and provide documentation that supports every figure. If a lender asks for additional documents, respond quickly. Speed and completeness are two of the strongest signals you can send as a self-employed borrower with bad credit.
Remember that submitting a request does not obligate you to accept any loan offer. You can compare offers, ask questions, and choose the one that fits your budget. Participating dealers or lenders may contact you after you submit your request, so be prepared for follow-up calls and have your documents ready to share. The more prepared you are, the smoother the process will go.
Securing a car loan as a self-employed borrower with bad credit is entirely possible when you treat proof of income as a project rather than an obstacle. Gather your tax returns, profit and loss statements, and bank statements early. Build a paper trail for gig and cash income. Write a short explanation letter if your documents need context. Then organize everything into a clean, consistent file before you apply. Lenders are not looking for perfection; they are looking for clarity and stability. Show them both, and you will be in a much stronger position to get approved and drive away in the vehicle you need.