Documents Needed for Bad Credit Car Loan Approval
Gather the right documents for bad credit car loan approval and avoid delays. A complete file can speed up your application and improve your terms.
By Valerie Turner
Your credit score is not the only number that determines whether you drive off the lot in a reliable vehicle. Lenders weigh your income stability, residency history, and ability to document your identity just as heavily as they weigh your past credit missteps. When you apply for a bad credit car loan, the paperwork you bring to the table often matters more than the score itself. A complete, organized file signals responsibility and reduces the risk that a lender perceives, which can translate into an approval and a lower interest rate. This guide walks you through every document you will likely need, explains why each one matters, and shows you how to prepare a submission that gets results the first time.
The Core Document Checklist for Bad Credit Auto Loan Applications
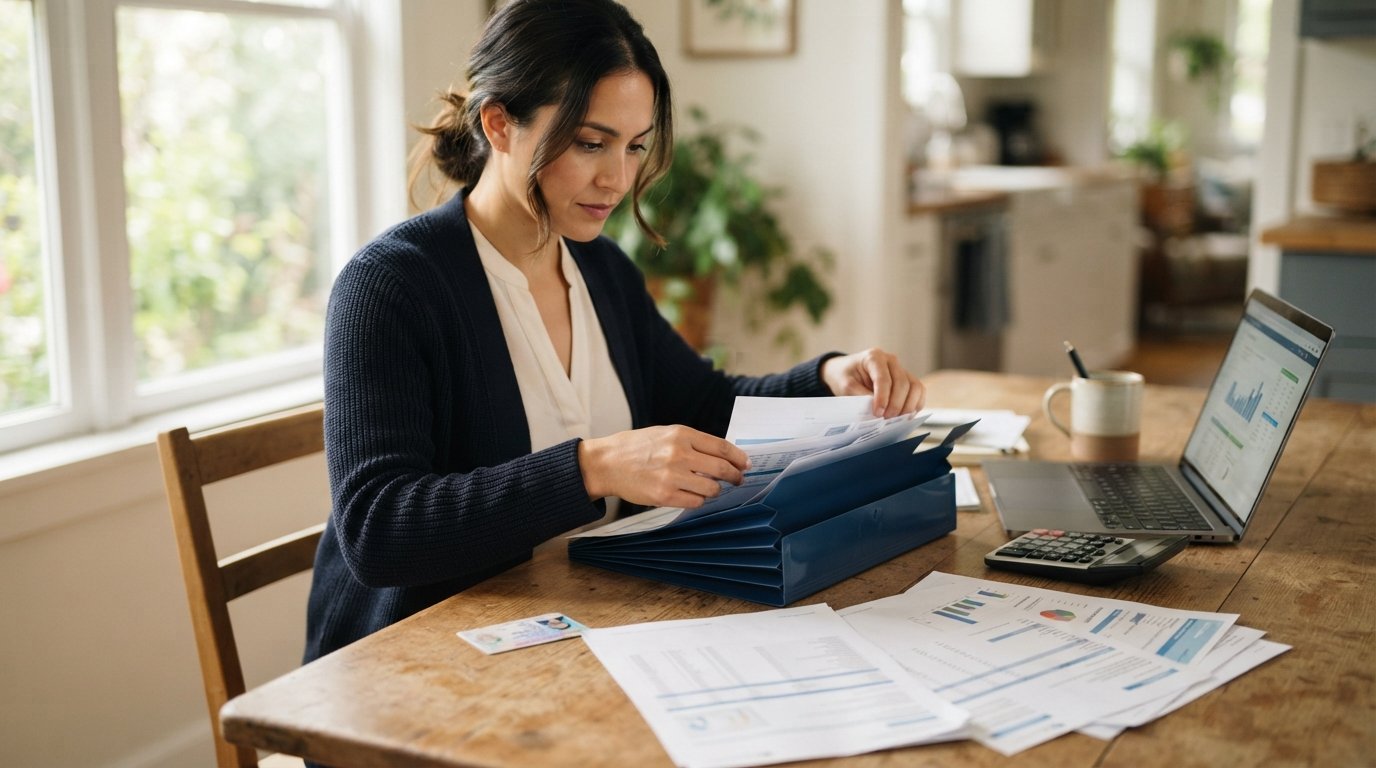
Most lenders that work with credit-challenged borrowers ask for a standard set of documents. These items prove three things: who you are, where you live, and how you will repay the loan. Missing even one piece can stall your application for days or cause an automatic denial. Gather these core documents before you start comparing offers.
First, you need a government-issued photo ID. A valid driver's license is ideal because it also proves you are legally permitted to operate the vehicle. A state ID card or passport can work in some cases, but a driver's license simplifies the process. Second, you need proof of income. Lenders typically want to see your two most recent pay stubs, or a letter from your employer if you were recently hired. If you receive direct deposit, a bank statement showing recurring deposits can supplement your pay stubs. Third, you need proof of residence. A utility bill, lease agreement, or mortgage statement dated within the last 30 to 60 days usually satisfies this requirement. Finally, you need a list of personal references. Lenders may contact these individuals to verify your identity and stability, so choose people who know you well and will answer their phone.
Here is a quick summary of the core documents needed for bad credit car loan approval:
- Government-issued photo ID (driver's license preferred)
- Recent pay stubs or an employment verification letter
- Utility bill, lease, or mortgage statement for proof of residence
- Names and phone numbers of three to five personal references
Having these four categories ready before you apply puts you ahead of most applicants. Lenders appreciate a clean, complete file because it reduces their administrative work and signals that you take the loan seriously. If you are missing a document, ask the lender whether an alternative form of proof is acceptable. Many subprime lenders are flexible with format as long as the information is verifiable.
Special Documentation for Self-Employed and Gig-Economy Income
If you earn money through freelance work, ride-share driving, delivery apps, or your own business, standard pay stubs will not tell the full story. Lenders know that self-employed income can be volatile, so they ask for more evidence to confirm that your earnings are steady enough to cover a monthly car payment. Expect to provide two years of federal tax returns, often with all schedules attached. If you have not been self-employed for two full years, provide whatever returns you have plus a year-to-date profit and loss statement prepared by you or your accountant.
Bank statements are your best friend in this situation. Lenders may ask for three to six months of personal and business bank statements to verify that deposits are consistent. Highlight recurring deposits from platforms like Uber, Lyft, DoorDash, or Upwork. A letter from your accountant or a signed affidavit of income can also help, especially if your tax returns show deductions that lower your reported income. Some lenders accept 1099 forms as a supplement, but they usually want to see the full tax return to confirm net earnings.
Gig workers should prepare a simple income summary that lists each platform, the gross amount received, and the date range. This is not a formal requirement, but it makes the lender's job easier and speeds up underwriting. Keep in mind that a connection service like StartAutoLoan can match you with lenders who are experienced in evaluating non-traditional income. That reduces the guesswork and the back-and-forth.
Bank Statements, Down Payment Proof, and Insurance Requirements
Bank statements serve two purposes in a bad credit car loan application. They verify your income if you are self-employed, and they show the lender that you have money available for a down payment and for the first few payments. Most lenders want to see at least 30 to 60 days of statements. If you are applying with a co-borrower, provide their statements as well. A healthy balance and a history of on-time bill payments in your account can offset some credit concerns.
Proof of down payment is increasingly important for bad credit approvals. Lenders often require a down payment of 10 to 20 percent, and they want to see that the funds are genuinely yours. A bank statement showing the down payment sitting in your account for at least a few weeks is ideal. If the money is a gift from a family member, ask the giver to sign a gift letter stating that the funds do not need to be repaid. Cash on hand is harder to verify, so deposit it into your account well before you apply.
Insurance requirements vary by lender and state, but you should be ready to show proof of full coverage insurance before you finalize the loan. Some lenders require comprehensive and collision coverage on the vehicle you are financing. Get a quote before you shop so you know the monthly cost and can factor it into your budget. Having an insurance card or binder ready at signing prevents last-minute delays. If you are unsure how much coverage you need, ask the lender for their minimum requirements in writing.
How a Streamlined Application Reduces Back-and-Forth
Gathering documents is only half the battle. The other half is submitting them to the right lender in the right format. A connection service streamlines this process by collecting your information once and matching you with lenders who are likely to approve your application based on your credit profile and documentation. Instead of applying to five lenders separately and uploading the same pay stubs five times, you submit one request and receive multiple offers to compare. This saves time and reduces the risk of errors that can lead to denials.
When you use a connection service, you can also ask questions about which documents each lender requires before you commit. Some lenders accept alternative proof of income, such as bank statements instead of pay stubs, while others are strict about tax returns. Knowing these details upfront helps you prepare a complete file for the lender you choose. For a deeper look at how to navigate the process with challenged credit, see our guide on car loans with no down payment and bad credit, which explains how down payment requirements interact with credit approval.
Remember that AutoTitleLoan.com is a connection service, not a direct lender. Submitting a request does not obligate you to accept any loan offer, and participating dealers or lenders may contact you with options. This structure gives you control over the final decision while still benefiting from a faster, more organized application process. Prepare your documents, review each offer carefully, and choose the loan that fits your budget rather than the first approval that arrives.
Organizing Your Paperwork for a Smoother Approval
Create a digital folder on your phone or computer with clear subfolders: identification, income, residence, references, bank statements, down payment, and insurance. Name each file descriptively, such as "paystub-Jan-2026.pdf" or "utility-bill-Dec-2025.pdf." When a lender requests a document, you can send it within minutes instead of scrambling through drawers. Print a set of copies for in-person dealership visits as well. A physical folder with tabbed sections makes a strong impression and keeps the meeting on track.
Check expiration dates on your ID and insurance documents before you apply. An expired license or lapsed policy can cause an automatic denial or a delay that lasts weeks. If your license is up for renewal, handle that first. Also verify that your address matches across your ID, bank statements, and utility bills. Lenders use address consistency as a fraud check, and mismatches trigger extra verification steps. If you recently moved, update your address with your bank and utility providers before submitting the application.
Finally, be honest about your income and employment. Lenders verify information through databases, employer calls, and tax transcripts. Inflating your income or omitting a job can lead to a denial and may be flagged as fraud. If your income is irregular, provide context in a brief cover letter that explains the pattern and why it is stable. A straightforward explanation paired with solid documentation goes a long way toward building trust with a subprime lender.
Documents That Can Strengthen a Weak Credit File
Beyond the required items, certain documents can improve your chances of approval or a better interest rate. A letter of explanation for past credit issues, such as a bankruptcy or a period of unemployment, shows lenders that the problem was temporary and that you have recovered. Keep it short, factual, and forward-looking. Proof of additional income, such as a side job or child support, can boost your debt-to-income ratio calculation. A co-borrower with strong credit and income can also transform a marginal application into an approval, though both parties share responsibility for the loan.
If you have completed a credit counseling program, include a certificate of completion. Some lenders view this as evidence of financial responsibility. Similarly, a letter from a current or past landlord confirming on-time rent payments can serve as a substitute for a traditional credit reference. These supplemental documents are not always required, but they add weight to your file when your credit score is the weakest part of your application.
Keep your documents current throughout the process. Pay stubs and bank statements expire quickly, and lenders may ask for updated versions if underwriting takes more than a few weeks. Set a reminder to refresh your file every 30 days until you close the loan. This small habit prevents the frustration of a last-minute request that delays your vehicle purchase.
Preparing the right documents turns a stressful bad credit car loan application into a manageable checklist. Start with the core items, add the special documentation for your income type, and organize everything in a way that makes submission effortless. A connection service can match you with lenders who understand your situation, but the quality of your paperwork is what ultimately moves your application from pending to approved. Gather your documents, review them for accuracy, and apply with confidence.