Dealer Financing vs Online Lender for Bad Credit Auto Loans
Compare dealer financing and online lenders for bad credit auto loans. Learn how to spot rate markups, compare offers, and save money.
By Wendy Foster
If you have bad credit and need a car, the financing decision can feel like a high-stakes puzzle. You walk onto a dealer lot, and the finance manager offers to "work with your credit." Or you open your laptop and see ads for online lenders promising fast approvals. Both paths can get you behind the wheel, but they work in very different ways, and the costs can vary dramatically. Understanding the real differences between dealer financing and online lending networks is the key to avoiding a costly mistake and protecting your wallet for years to come.
How Dealer Financing Works for Bad Credit Borrowers
Dealer financing is exactly what it sounds like: the dealership arranges the loan for you. In most cases, the dealer does not actually lend the money itself. Instead, it works with a network of banks, credit unions, and specialty finance companies. The finance manager submits your application to these lenders and then presents you with the offer or offers that come back. For someone with bad credit, this can feel convenient because you are already at the dealership, and the finance manager handles the paperwork.
However, there is a catch that every bad credit shopper should understand. Dealers often have the ability to mark up the interest rate on the loan they present to you. This means the lender approves you at one rate, and the dealer increases that rate before showing it to you. The difference between the approved rate and the rate you sign is profit for the dealership, often called a dealer reserve. This markup is not always disclosed clearly, and it can add hundreds or even thousands of dollars in extra interest over the life of the loan. While not every dealer marks up rates, the practice is common enough that you should always ask whether the rate you are being offered is the buy rate (the lender's actual approved rate) or a marked-up rate.
Dealer financing also tends to limit your options. The finance manager might only send your application to a handful of lenders, and those lenders may be the ones that offer the dealer the best reserve or the fastest funding. You have no way of knowing whether a better offer exists elsewhere. For borrowers with bad credit, this lack of competition can be especially costly because subprime rates are already high, and a markup on top of an already elevated rate can push your payment into dangerous territory.
That said, dealer financing is not inherently bad. Some dealerships, particularly those that specialize in bad credit or subprime lending, have established relationships with lenders who understand credit challenges. They may be able to get you approved when other lenders say no. The convenience of driving off the lot the same day is also a real benefit. The key is to go in with your eyes open and to understand the numbers before you sign anything.
How Online Lending Networks Approach Bad Credit Auto Loans
Online lending networks operate on a different model. Instead of one finance manager submitting your application to a few lenders, an online connection service sends your information to a broader network of participating lenders and dealers. These platforms are not direct lenders themselves; they are matchmaking services that connect borrowers with financing options. For people with bad credit, no credit history, or past bankruptcies, this can open doors that a single dealership might not.
The core advantage here is competition. When multiple lenders see your application, they are effectively bidding for your business. You receive several offers with different rates, terms, and down payment requirements. This transparency puts you in the driver's seat. You can compare offers side by side and choose the one that fits your budget, rather than accepting the first number a finance manager slides across the desk. For a bad credit auto loan, where even a small difference in interest rate can mean thousands of dollars over the loan term, this competition is invaluable.
Another benefit is the lack of obligation. Reputable online connection services make it clear that submitting a request does not commit you to accepting any loan. You can review the offers, ask questions, and walk away if nothing works for you. This low-pressure environment is a stark contrast to the sales floor, where you might feel rushed or pressured to sign on the spot. For borrowers who have been rejected by traditional lenders in the past, the ability to explore options without commitment can be a welcome relief.
Online platforms also tend to be more transparent about the process. You can often see the lender's name, the estimated rate range, and the terms before you agree to anything. Some platforms provide educational resources to help you understand what to look for in a bad credit auto loan. This transparency is particularly important for subprime borrowers, who may be targeted by predatory lenders. A good online connection service will not guarantee approval, but it will give you a clearer picture of what is available.
If you are exploring this route, you can start by using a connection service to request auto loan options from a network of lenders. These platforms are designed to help people who have faced rejection elsewhere, and they can be a useful first step in your research. Just remember that the platform itself is not lending you money; it is connecting you with lenders who may be able to help.
Key Factors to Compare: Rates, Terms, Convenience, and Transparency
When you are deciding between dealer financing and an online lender, you need a framework for comparison. The following factors are the most important ones to weigh, especially when your credit is less than perfect.
Interest rate and total cost. This is the single most important factor. A lower interest rate can save you a significant amount of money over the life of the loan. Dealer financing may come with a marked-up rate, while online lenders may offer more competitive rates because of the competitive bidding process. Always compare the annual percentage rate (APR), not just the monthly payment. The APR includes fees and gives you a truer picture of the loan's cost.
Loan terms and flexibility. The length of the loan matters. A longer term lowers your monthly payment but increases the total interest you pay. Dealer financing might push you toward a longer term to make the payment fit your budget, which can keep you upside down on the car for years. Online lenders may offer a range of terms, allowing you to choose a balance between payment size and total cost. Also, check for prepayment penalties; you do not want to be punished for paying off the loan early.
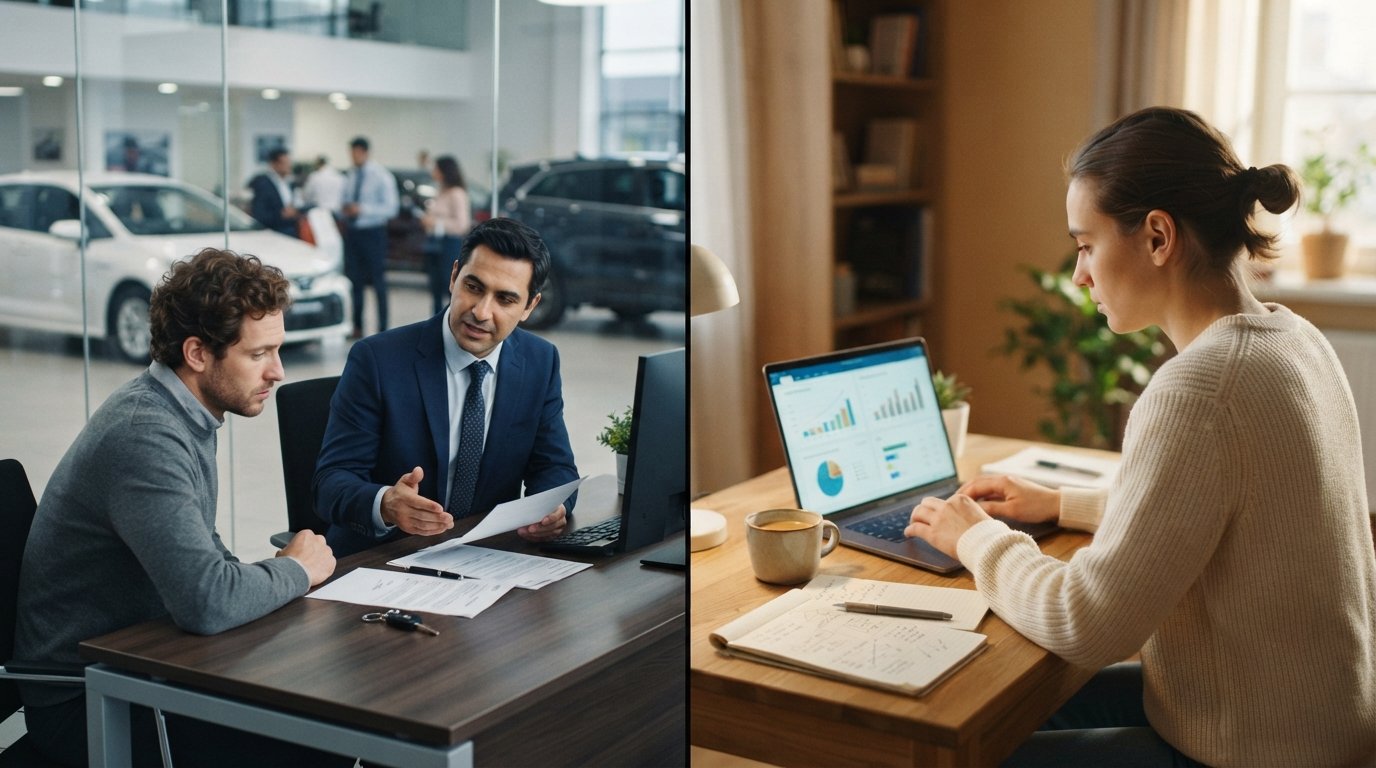
Convenience and speed. Dealer financing wins on convenience if you want to handle everything in one place and drive home the same day. Online lending networks can also be fast, but you may need to wait for offers to come in and then complete the paperwork with the chosen lender. The trade-off is often between speed and choice. If you have the time to compare, the online route can be more financially rewarding.
Transparency and pressure. Dealer financing can be opaque. You may not know if the rate has been marked up, and you may feel pressure to sign quickly. Online lending networks are generally more transparent, with clear disclosures and no obligation to accept an offer. For bad credit borrowers who have been burned before, this transparency can be a major comfort.
To make this concrete, here is a simple comparison framework you can use:
- Dealer financing: Convenient, one-stop shop, but potential rate markup and limited lender options.
- Online lending network: Multiple offers, more transparency, no obligation, but requires more time and paperwork on your end.
- Best for bad credit: Often an online network because competition can drive down rates, but a reputable bad credit dealership can also be a good option if you negotiate carefully.
For a deeper dive into how dealer financing stacks up against traditional bank loans, you might find our comparison of dealer financing versus bank loans helpful. The same principles of rate markup and limited options apply, and understanding those dynamics can inform your decision here as well.
The Hidden Costs of Dealer Financing and How to Spot Them
Dealer financing can come with several hidden costs that are not always obvious at first glance. The most significant is the interest rate markup, as mentioned earlier. But there are others. Dealers may add fees for extended warranties, gap insurance, or other add-ons that get rolled into the loan. These add-ons increase the amount you finance, which means you pay interest on them as well. While some of these products can be valuable, they should be evaluated separately and not simply accepted because they are presented as part of the financing package.
Another hidden cost is the potential for a longer loan term. If the dealer stretches your loan to 72 or 84 months to make the payment affordable, you may end up paying far more in interest than you realize. And because cars depreciate quickly, a long loan term can leave you owing more than the car is worth, a situation known as being upside down. This can be a serious problem if you need to sell the car or if it is totaled in an accident.
To spot these costs, ask for a full breakdown of the loan, including the price of the car, the interest rate, the APR, the loan term, and any add-on products. Do not sign anything until you have reviewed this breakdown and compared it to other offers. If the finance manager is reluctant to provide this information, that is a red flag.
Advantages of Online Lending Networks for Bad Credit Borrowers
Online lending networks offer several distinct advantages that can be particularly valuable for people with bad credit. The first is access to a wider range of lenders. Traditional banks often have strict credit score requirements, and a single dealership may only work with a limited set of lenders. An online network can connect you with lenders who specialize in subprime auto loans, including those who consider alternative factors like income stability and down payment.
The second advantage is the ability to compare offers side by side. When you receive multiple offers, you can see exactly what each lender is offering in terms of rate, term, and fees. This makes it much harder for a single lender to take advantage of you. You can use the offers as leverage, even if you ultimately decide to go with dealer financing, because you will know what the market looks like.
The third advantage is the low-pressure environment. You can apply from home, review offers on your own time, and ask questions without a salesperson hovering over you. This can lead to more thoughtful decision-making, which is especially important when you are dealing with the financial strain of bad credit. There is no obligation to accept any offer, so you can walk away if the terms are not right.
For those who are concerned about the application process, many online connection services offer a streamlined form that takes just a few minutes to complete. You provide some basic information about yourself and your vehicle needs, and the platform matches you with lenders. This can be a much less intimidating process than sitting in a dealership finance office.
When Dealer Financing Might Be the Better Choice
Despite the potential drawbacks, there are situations where dealer financing can be the better choice. If you have very bad credit and have been rejected by multiple online lenders, a dealership that specializes in subprime financing may have relationships with lenders who are willing to take a chance on you. These dealerships often have more flexibility and can work with you to find a solution.
Convenience is another factor. If you need a car immediately and do not have the time to wait for online offers, dealer financing can get you on the road faster. Some dealerships offer same-day approval and delivery, which can be a lifesaver in an emergency. However, even in this situation, you should still ask about the rate and terms and try to negotiate.
Finally, if you have a trade-in or a down payment, dealer financing can sometimes be more flexible in how those are applied. A dealer may be able to structure the deal in a way that works for your specific situation, whereas an online lender might have more rigid requirements. The key is to go in with a clear understanding of what you can afford and to be prepared to walk away if the terms are not favorable.
Practical Steps to Get the Best Bad Credit Auto Loan
Regardless of which path you choose, there are steps you can take to improve your chances of getting a fair deal. The following numbered list outlines a process you can follow:
- Check your credit report. Before you apply for anything, get a free copy of your credit report and review it for errors. Disputing inaccuracies can improve your score and help you qualify for better rates.
- Save for a down payment. A larger down payment reduces the amount you need to finance and can lower your interest rate. Even a modest down payment can make a difference.
- Get pre-approved online. Use an online connection service to see what offers are available. This gives you a baseline and leverage when negotiating with a dealer.
- Compare dealer offers carefully. If you choose dealer financing, ask for the buy rate and compare it to your online offers. Do not be afraid to negotiate.
- Read the contract. Before you sign, read every line of the contract and make sure you understand all the terms, including the APR, the loan term, and any add-on products.
Following these steps can help you avoid the most common pitfalls and secure a loan that fits your budget. It also puts you in a stronger position to negotiate, whether you are at a dealership or working with an online lender.
Protecting Yourself from Predatory Lending
Bad credit borrowers are often targets for predatory lenders. These lenders may charge excessively high interest rates, hide fees, or pressure you into loans you cannot afford. To protect yourself, be wary of any lender that guarantees approval before looking at your information, asks for a fee upfront, or rushes you through the process. A legitimate lender will be transparent about the costs and will give you time to review the documents.
It is also important to understand that there is no obligation to take a loan. If an offer feels wrong, you can walk away. Do not let anyone pressure you into signing something you are not comfortable with. Trust your instincts, and if something seems too good to be true, it probably is.
Finally, consider working with an independent connection service that is not a direct lender. These platforms can connect you with multiple lenders and give you the information you need to make an informed decision. They are not making the loan themselves, so their incentive is to help you find a match, not to sell you a specific product.
Choosing between dealer financing and an online lender for a bad credit auto loan comes down to understanding the trade-offs. Dealer financing offers convenience but may come with hidden markups and limited options. Online lending networks offer competition and transparency but require more effort on your part. By comparing offers, asking the right questions, and protecting yourself from predatory practices, you can find a loan that works for your budget and your credit situation. Take your time, do your research, and remember that you have more power than you think. StartAutoLoan