Dealer Financing vs Bank Loan for Bad Credit: Which Wins?
Compare dealer financing vs bank loan for bad credit, including costs, approval odds, and how to use both to negotiate a lower rate.
By Valerie Turner
Your credit score is not a verdict on your future, but it can feel like one when you are sitting in a dealership finance office or staring at a bank loan application. If you have bad credit, the choice between dealer financing and a bank loan can shape not only your monthly payment but also your total cost of ownership for years. The good news is that both paths can work, and the better news is that you are not limited to just one. Understanding how each option really operates, where the money comes from, and what leverage you actually have will help you make a decision that fits your budget instead of a salesperson's quota.
How Dealer Financing Really Works Behind the Scenes
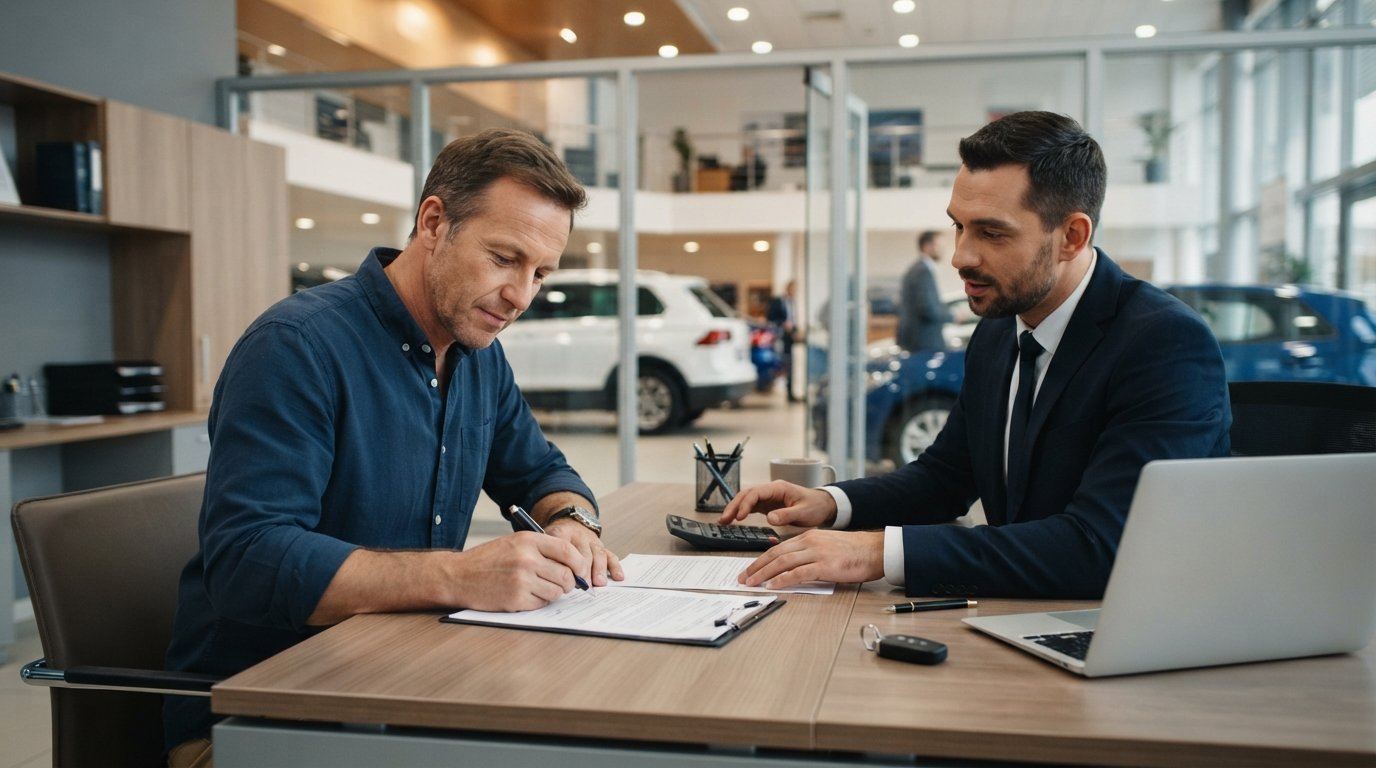
Dealer financing is not a single lender. It is a network. When you fill out a credit application at a dealership, the finance manager sends it to a group of lenders the store works with regularly. These can include banks, credit unions, captive finance companies owned by automakers, and subprime lenders that specialize in higher risk borrowers. The dealer acts as a middleman, and in many cases, the dealer is allowed to mark up the interest rate above what the lender approved, within legal limits, and keep a portion of that spread as profit.
That markup is not automatically a bad thing, but it is a reason to pay attention. A dealer might quote you 14 percent when the lender actually approved you at 11 percent. The difference goes to the dealership, not the bank. This is why comparing the annual percentage rate you are offered against outside preapproval numbers matters so much. Dealers also have access to promotional rates from manufacturers, but those usually require excellent credit and rarely apply to bad credit buyers.
Where dealer financing shines is convenience and flexibility. You can shop, negotiate the vehicle price, and arrange financing in one visit. Dealers also have relationships with subprime lenders that you might never find on your own, and they know which lenders are most likely to approve a file with a recent bankruptcy or a thin credit history. For someone who has been rejected by multiple banks, that network can be the difference between driving home and taking the bus.
Bank and Credit Union Standards for Bad Credit Applicants
Banks and credit unions are direct lenders, which means they use their own money and their own underwriting rules. For bad credit applicants, those rules are usually strict. Most traditional banks want to see a minimum score in the mid 600s, a clean recent payment history, and a debt to income ratio that leaves room for a new car payment. If your score is in the 500s or you have a recent collection account, a conventional bank loan is likely out of reach.
Credit unions are often more flexible, especially if you have an existing relationship. Some credit unions offer first time buyer programs or credit builder loans that can help members with limited or damaged credit. Still, even a generous credit union will usually charge a higher rate for bad credit, and approval is never guaranteed. The application process is also slower than dealer financing because you are dealing with a single institution's timeline rather than a network of lenders responding in hours.
Bank loans do offer one clear advantage: transparency. You know exactly who is lending the money, and there is no rate markup hidden in the deal. If you can get approved, a bank or credit union loan often comes with lower fees and simpler terms. The challenge is getting approved in the first place, which is why many bad credit buyers end up at the dealership by default.
Cost Differences, Convenience, and Negotiating Power
Cost is where the two options diverge most. Dealer financing can be more expensive because of rate markup and because dealers sometimes bundle add ons like extended warranties or gap insurance into the loan. Those products are not inherently bad, but they increase the amount financed and the total interest you pay. A bank loan, by contrast, is usually a straightforward principal and interest agreement with fewer opportunities for add ons.
Convenience favors the dealer. You can walk in with no preapproval, and the finance office will work to find a lender. That speed matters if you need a car immediately. Negotiating power is more complicated. When you finance at the dealership, the vehicle price and the financing are intertwined, which makes it harder to tell whether you got a good deal on either one. When you walk in with a bank preapproval, you negotiate as a cash buyer, which typically gives you more leverage on the vehicle price.
Here is a practical way to compare the two offers side by side:
- Annual percentage rate: Compare the APR, not just the monthly payment. A longer term can lower the payment while raising the total cost.
- Total finance charge: Add up all interest and fees over the life of the loan. This is the real cost of borrowing.
- Add ons and fees: Ask for an itemized list. Dealer financing often includes products a bank loan does not.
- Prepayment penalties: Confirm you can pay off the loan early without a fee, especially if you plan to refinance later.
Once you have those numbers, the cheaper option is usually the one with the lowest total finance charge, not the lowest monthly payment. A five year loan at a higher rate can cost thousands more than a four year loan at a lower rate, even if the monthly difference feels small.
How a Connection Service Gives You Access to Both Networks
The smartest approach for bad credit buyers is not to choose one side blindly but to get exposure to both. That is exactly what an independent connection service does. Instead of applying to a single bank or walking into one dealership, you submit one request and get matched with participating lenders and dealers who work with challenged credit. This widens your options without forcing you to spend weeks filling out applications.
Platforms like StartAutoLoan connect consumers with auto loan financing options and function as a connection service rather than a direct lender. That distinction matters: the platform does not make the loan, but it puts your request in front of lenders and dealers who may be willing to approve it. For someone who has faced rejection, that is a useful first step because it turns a closed door into a set of possibilities.
You can also use a connection service alongside your own research. For example, if you are considering a no down payment scenario, our guide on a car loan with no down payment and bad credit explains how to structure that request without overextending your budget. The same principle applies here: gather multiple offers, compare them on total cost, and then negotiate from a position of information rather than desperation.
When Dealer Financing Makes More Sense
Dealer financing tends to be the better fit when your credit file is complicated. Recent bankruptcy, multiple collections, or a very thin credit history can make bank underwriting shut down quickly. Dealers work with subprime lenders every day and know which ones are most likely to say yes to a specific profile. If you need a vehicle soon and you do not have a preapproval, the dealership finance office may be your fastest route to a yes.
Dealer financing also makes sense when the manufacturer is offering incentives. Sometimes a captive lender will offer a rebate or a promotional rate that is only available through the dealership. Those offers rarely apply to bad credit, but it is worth asking. If the dealer can combine a rebate with a subprime approval, the total deal might beat a standalone bank loan even with a higher rate.
The key is to separate the vehicle negotiation from the financing negotiation. Agree on the out the door price first, then discuss financing. If the finance manager cannot beat your outside offer, you can walk away or ask them to match it. Dealers want to sell cars, and a finance manager who knows you have another offer is more likely to sharpen the pencil.
When a Bank Loan or Credit Union Loan Wins
A bank or credit union loan is often the better choice when you can get approved. The rate is usually lower, the fees are fewer, and there is no rate markup. If you have spent the past year rebuilding your credit and your score has crossed into the mid 600s, a credit union may approve you at a rate that saves you thousands over the life of the loan. That is especially true if you are buying a newer used car or a new car with a strong resale value.
Bank loans also give you a clean negotiating position. You can shop for the car as a cash buyer, which means the dealer cannot use financing as a lever to hide the true price. You can also shop for the loan separately from the car, which makes it easier to compare offers. That separation is one of the most reliable ways to avoid paying too much for either the vehicle or the money.
If you are not sure whether you qualify, it is worth applying to a credit union before you visit a dealership. A preapproval costs nothing in most cases, and it gives you a benchmark. Even if you end up using dealer financing, you will know whether the dealer's offer is competitive or expensive.
A Step by Step Framework for Bad Credit Buyers
Instead of treating this as an either or decision, treat it as a sequence. The goal is to gather information before you commit, and to keep the vehicle price and the financing separate for as long as possible. Here is a framework that works for most bad credit situations:
- Check your credit reports first. Look for errors and dispute anything inaccurate. A single removed collection can change which lenders will approve you.
- Get a preapproval from a bank or credit union if possible. Even a rejection tells you something about your profile and what you need to improve.
- Submit a request through a connection service. This exposes your file to multiple lenders and dealers without dozens of separate applications.
- Compare offers on total finance charge, not monthly payment. Ask for the APR, the term, and an itemized list of fees.
- Negotiate the vehicle price separately. Agree on the out the door price before you discuss financing, and do not let the finance office bundle add ons without your explicit approval.
After you have offers in hand, take a day to compare them. The difference between a 12 percent loan and a 16 percent loan on a 15,000 dollar balance is more than 3,000 dollars over five years. That is real money, and it is worth the extra effort to get the lower number. If the dealer can match your bank preapproval, great. If not, you have a clear reason to walk away.
Mistakes That Cost Bad Credit Buyers Money
The most common mistake is focusing on the monthly payment instead of the total cost. A dealer can stretch the term to 72 or 84 months to make a payment fit, but that increases the interest you pay and leaves you upside down on the vehicle for years. Another common mistake is accepting add ons without understanding them. Extended warranties and gap insurance can be useful, but they should be priced separately and compared, not rolled into the loan without discussion.
A third mistake is applying to too many lenders in a short window. Each hard inquiry can ding your score slightly, and a cluster of applications can make you look desperate to underwriters. A connection service helps here because one request can reach multiple lenders without a separate hard pull for each one. Finally, many buyers forget to ask about prepayment penalties. If you plan to refinance in a year or two, a penalty can erase the savings you were counting on.
Bad credit does not mean you have no options. It means you need to be more deliberate about which options you pursue. Dealer financing and bank loans each have a role, and the best outcome usually comes from using both: a preapproval to set your benchmark, a connection service to widen your network, and a clear comparison of total cost before you sign anything. If you do that, you give yourself the best chance of driving away with a loan you can actually afford.